Machines rarely fail without warning. A bearing runs hot for weeks, a boiler’s pressure readings drift or a crane’s cables show wear long before something breaks. Businesses that catch these signs early avoid expensive breakdowns, and they also tend to look better to insurers. Maintenance isn’t just an engineering task. It’s one of the most practical ways to manage the cost of engineering insurance and protect your claims.
Why Insurers Care About Maintenance
Engineering insurance covers machinery, plant and construction risks, where the likelihood of loss depends heavily on how equipment is looked after. A well-maintained machine is less likely to break down, catch fire or cause an accident than one that’s been neglected.
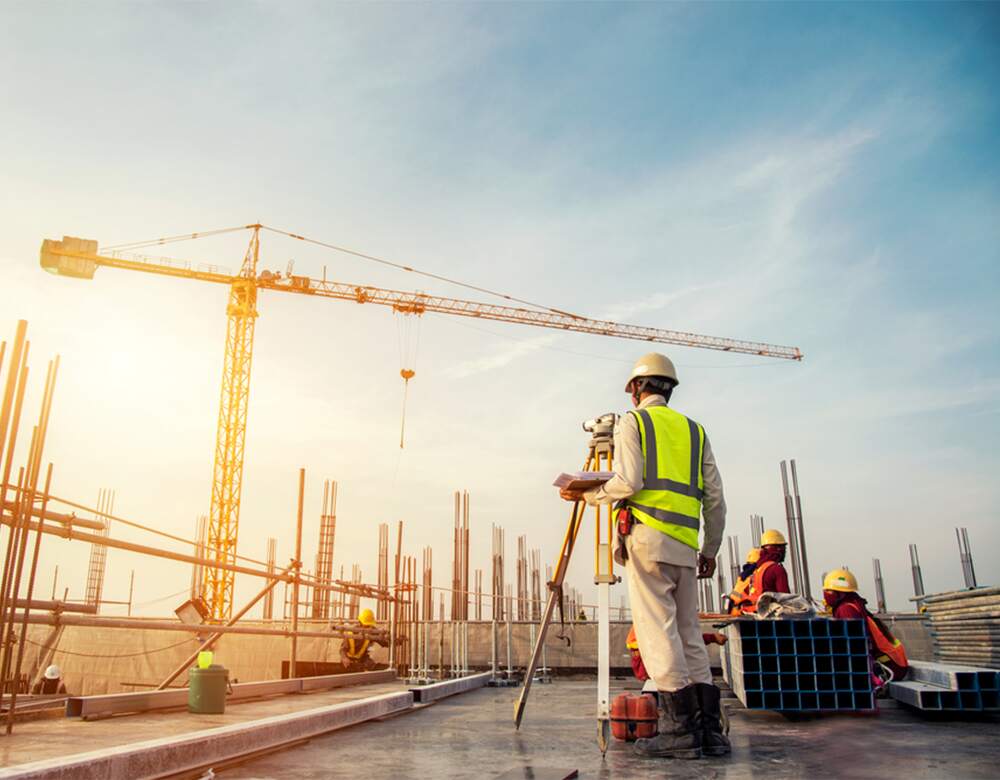
That applies on construction sites too. A contractor all risk policy covers works under construction, and the condition of cranes, hoists, scaffolding and temporary structures on site affects the risk of collapse, fire or accidental damage. Good maintenance practices reduce the chance of a claim in the first place.
Engineering Covers Where Maintenance Matters
Machinery breakdown insurance covers sudden and unforeseen damage to plant and machinery from internal causes, such as electrical faults or mechanical failure. Boiler and pressure plant insurance covers explosion or collapse of boilers and pressure vessels. Electronic equipment insurance protects computers, control systems and similar equipment.
In each case, the risk of loss depends heavily on how equipment is looked after. A well-serviced boiler is less likely to fail, and electronic systems kept in clean, climate-controlled rooms tend to last longer. Maintenance is the common thread running through all of them.
How Maintenance Affects Pricing
When underwriting a policy, insurers consider the age and type of equipment, how intensively it’s used, its maintenance history and its claims record. Businesses with documented maintenance programmes and low claims may be offered better terms at renewal than those with frequent breakdowns.
Premiums for engineering insurance aren’t set by maintenance alone, and no insurer can promise a specific discount for it. But maintenance influences two things insurers weigh closely: the likelihood of a loss and the size of any loss that does occur.
Planned Maintenance Versus Breakdown Repair
Breakdown repair means fixing machines after they fail. Planned or preventive maintenance means servicing them at scheduled intervals, based on manufacturer guidance or operating hours. Predictive maintenance goes further, using vibration analysis, thermography or oil testing to spot problems before they cause failure.
Insurers generally view planned and predictive approaches more favourably, because they reduce sudden, costly breakdowns. They also reduce downtime, which matters if you’ve bought business interruption cover linked to machinery losses. Keeping critical spares on hand can also shorten downtime after a failure.
Records Matter as Much as the Work
Maintenance that isn’t documented is hard to prove. Keep service logs, inspection reports, statutory test certificates for boilers, pressure vessels and lifting equipment, and records of parts replaced. Calibrate gauges and safety devices on schedule, because a faulty pressure gauge or relief valve can turn a minor fault into a serious loss.
These records help at renewal, when you can show insurers how equipment is managed. They help even more at claim time, when surveyors may check whether machines were maintained according to manufacturer recommendations and statutory requirements.
Maintenance and Claims
Most engineering policies exclude wear and tear, gradual deterioration and losses caused by operating machines beyond their design limits. Where neglect contributes to a breakdown, the insurer may question whether the loss falls under these exclusions.
Some policies also carry conditions requiring equipment to be kept in efficient working order. If a condition is breached and that breach is relevant to the loss, the claim could be affected, depending on the wording. Regular maintenance helps you meet those conditions.
Exclusions and Limits to Keep in Mind
Even with excellent maintenance, engineering policies have limits. Deductibles apply to each claim, sub-limits may apply to certain items and some types of damage, such as gradual corrosion or the failure of consumable parts, are typically excluded.
Read the policy wording and the Customer Information Sheet to understand what’s covered for each machine, how losses are valued and what conditions apply. Knowing these details helps you plan maintenance around the risks that matter most.
Common Mistakes Businesses Make
One common mistake is cutting maintenance budgets during lean periods, which often leads to costlier breakdowns later. Another is using unqualified technicians or non-standard spare parts, which can increase risk and raise questions during a claim.
Some businesses also forget to update insurers about major overhauls, upgrades or changes in how equipment is used. These changes can affect both risk and cover, so share them at renewal or sooner if significant.
Building a Maintenance Culture
Assign responsibility for maintenance schedules and records to named people, and review compliance regularly. Train operators to report unusual sounds, vibrations or readings promptly.
Share your maintenance programme with your insurer or broker. Some insurers offer risk inspections and engineering advice, which can help you improve practices and strengthen your position at renewal.
Good maintenance protects machines, people and production at the same time. It’s also one of the clearest signals to an insurer that your business manages risk seriously.